Market overview and scope of the Civil Helicopter Market
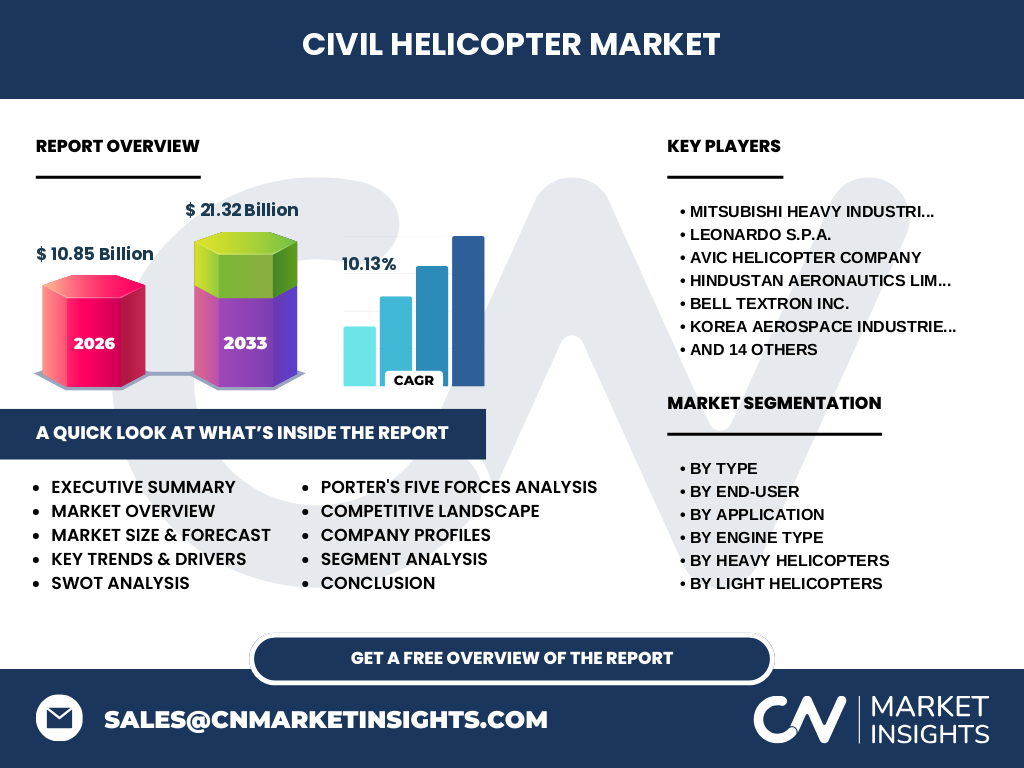
Our analysis indicates that the Civil Helicopter Market market size is valued at 10.85 Billion in 2026. This sector encompasses commercial, government, and private rotorcraft operations globally, vital for remote access, medical transit, and infrastructure support governed by stringent EASA and FAA airworthiness standards.
Structural Growth Drivers and Market Restraints
Growth is propelled by rising offshore energy exploration and emergency medical service demands. However, supply chain bottlenecks for titanium forgings and stringent carbon emission mandates by regulatory bodies like the ICAO act as key restraints, challenging profit margins for OEMs.
Emerging Industry Trends and Growth Patterns
The shift toward hybrid-electric propulsion and advanced avionics suite integration dominates Civil Helicopter Market industry trends. Operators increasingly prioritize low-noise signatures and digital health and usage monitoring systems (HUMS) to maximize fleet readiness and reduce operational downtime.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains and grounded non-essential charter fleets. Our research shows a robust recovery trajectory driven by a post-pandemic surge in utility transport, emergency medical services, and government procurement of heavy-lift platforms for disaster relief.
Competitive Landscape and Strategic Dynamics
Market concentration remains high, led by prime innovators such as Airbus Helicopters, Leonardo S.p.A., and Bell Textron Inc. Strategic dynamics involve aggressive portfolio electrification and localized manufacturing partnerships to navigate geopolitical export restrictions and tariffs.
Executive Summary of the Civil Helicopter Market Analysis
This comprehensive report highlights a dynamic expansion path for the Civil Helicopter Market analysis. With a robust projected valuation of 21.32 Billion by 2033, stakeholders must capitalize on turbine engine upgrades and specialized EMS applications to secure market share.
Long-Term Market Forecast from 2027 to 2033
The data suggests the market will expand rapidly from 2027 to 2033, achieving a compound annual growth rate of 10.13%. This acceleration is underpinned by replacement cycles for aging single-engine fleets and rising infrastructure spending in emerging economies.
Segmentation Analysis Across Categories and Applications
The market breaks down by Type (Light, Medium, Heavy), End-User (Government, Commercial, Private), Application (EMS, Corporate, Law Enforcement, Search and Rescue, Tourism, Utility), and Engine Type (Single-Engine, Twin-Engine), with sub-segments like firefighting and offshore support driving specialized demand.
Regional Market Performance and Geographic Distribution
Geographic performance varies significantly, with North America leading in private and corporate fleet volume, while the Asia-Pacific region demonstrates the fastest growth due to expanding offshore oil rigs and rising government investments in emergency medical infrastructure.
In-Depth Regional Review of Key Markets
North America benefits from mature MRO networks and high private ownership. Meanwhile, localized constraints in Europe center on strict noise abatement laws, pushing operators toward twin-engine turbine platforms equipped with advanced acoustic dampening rotors from innovators like Konner Helicopters.
Strategic Positioning of Leading Company Profiles
Industry stalwarts like Russian Helicopters and Hindustan Aeronautics Limited focus on utility and heavy-lift state contracts, whereas Western players such as MD Helicopters Inc. and Enstrom Helicopter Corporation target agile light single-engine training and law enforcement niches.
Porter's Five Forces Competitive Analysis
Supplier power is moderate-to-high due to specialized gearbox and turbine manufacturers. Threat of substitutes remains low for vertical takeoff and landing missions, though high capital requirements for type certification heavily restrict new market entrants.
Comprehensive SWOT Analysis of the Sector
Key strengths include unmatched point-to-point mobility, while weaknesses involve high fuel and maintenance intensity. Opportunities lie in autonomous cargo transport, threatened heavily by macroeconomic inflation and rising insurance underwriting costs for rotorcraft operators.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw aerospace-grade titanium and composite material suppliers to Tier-1 aerostructures manufacturers, OEM assembly lines, and finally to commercial operators and flight schools utilizing regional MRO hubs for ongoing airworthiness compliance.
Strategic Investment Insights and High-Potential Areas
High-potential investment areas center on aftermarket predictive maintenance software, sustainable aviation fuel (SAF) compatibility retrofits, and electric vertical takeoff infrastructure that complements traditional rotorcraft fleets in congested metropolitan airspaces.
Conclusion and Definitive Industry Takeaways
The Civil Helicopter Market presents robust opportunities for forward-thinking enterprises. Navigating regulatory evolution, embracing digital maintenance ecosystems, and aligning product portfolios with twin-engine safety demands will dictate long-term leadership.
Rigorous Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining global civil aviation registry datasets, primary stakeholder interviews with chief engineers, and secondary macroeconomic indicators such as national defense budgets and offshore rig counts.
Scope of the Report and Analytical Limitations
This report covers global civil rotorcraft manufacturing, aftermarket services, and operational deployments. Limitations include potential delays in official government import-export filings and unpredictable geopolitical shifts affecting foreign military-to-civil technology spin-offs.
Recent Developments, Partnerships, and Strategic Moves
Recent milestones feature strategic joint ventures by AVIC Helicopter Company and new STC approvals for advanced glass cockpit retrofits by firms like Eagle Copters, signaling an industry-wide push toward enhanced situational awareness and reduced pilot workload.